Dispensary payment processing lets a licensed cannabis store take non-cash payments and deposit the money into a business bank account. In New York, a processor does this within state cannabis rules and federal limits on banks and card networks. Cash stays your baseline, and a processor adds a way to get paid without filling the register drawer.
We are Dispensary Payment Processing, and our team provides payment processing built for dispensaries and licensed stores. This post covers the problems New York owners face at the counter and at the bank, and how we handle each one.
Why Cash Checkout Puts Your Store at Risk
Cash at the register means cash in the building, and theft risk grows with every dollar in the drawer and the safe. Secure storage, armored pickups and bank runs add cost on top of that risk. Each of those costs lands on your store every week. A drawer that holds less cash costs less to guard.
Cash also caps each sale at whatever the customer brought in. A customer who carries less than the cart costs has to cut the order or leave the line. Every end-of-day count then takes staff time and leaves room for counting errors.
What Federal Rules Mean for Your Payment Options
Federal law still lists adult-use cannabis as Schedule I. Marijuana sold under a state medical license moved to Schedule III in April 2026, and that order does not cover adult-use sales. Your payment options depend on which side of that line a sale falls on.
Card networks have acted against several cannabis payment methods since 2021, so a method that works this year can be shut down the next. Banks weigh the same federal rules when they decide whether to serve a dispensary. Take legal and tax questions to a cannabis attorney or CPA.
How We Handle Checkout at Your Counter
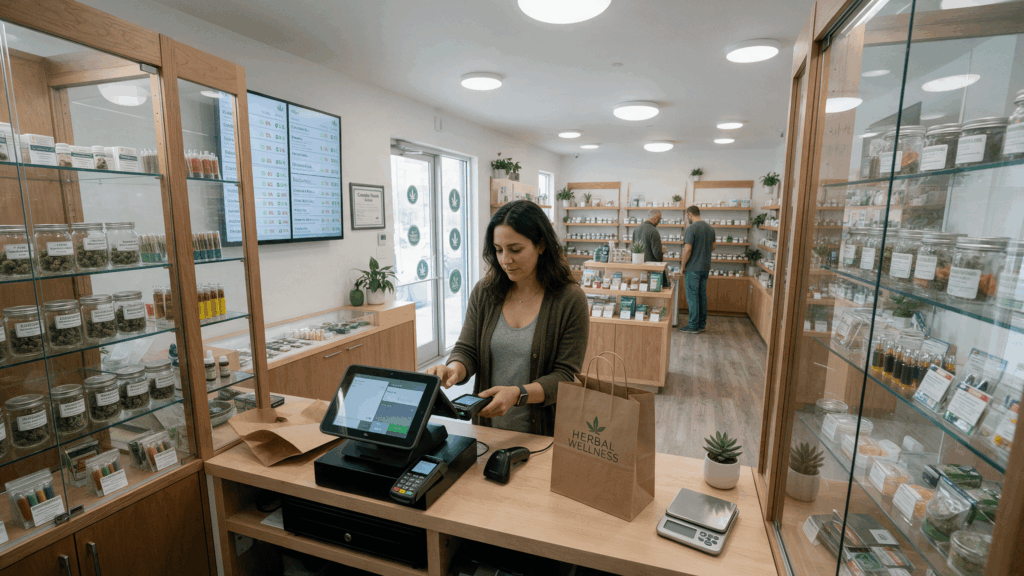
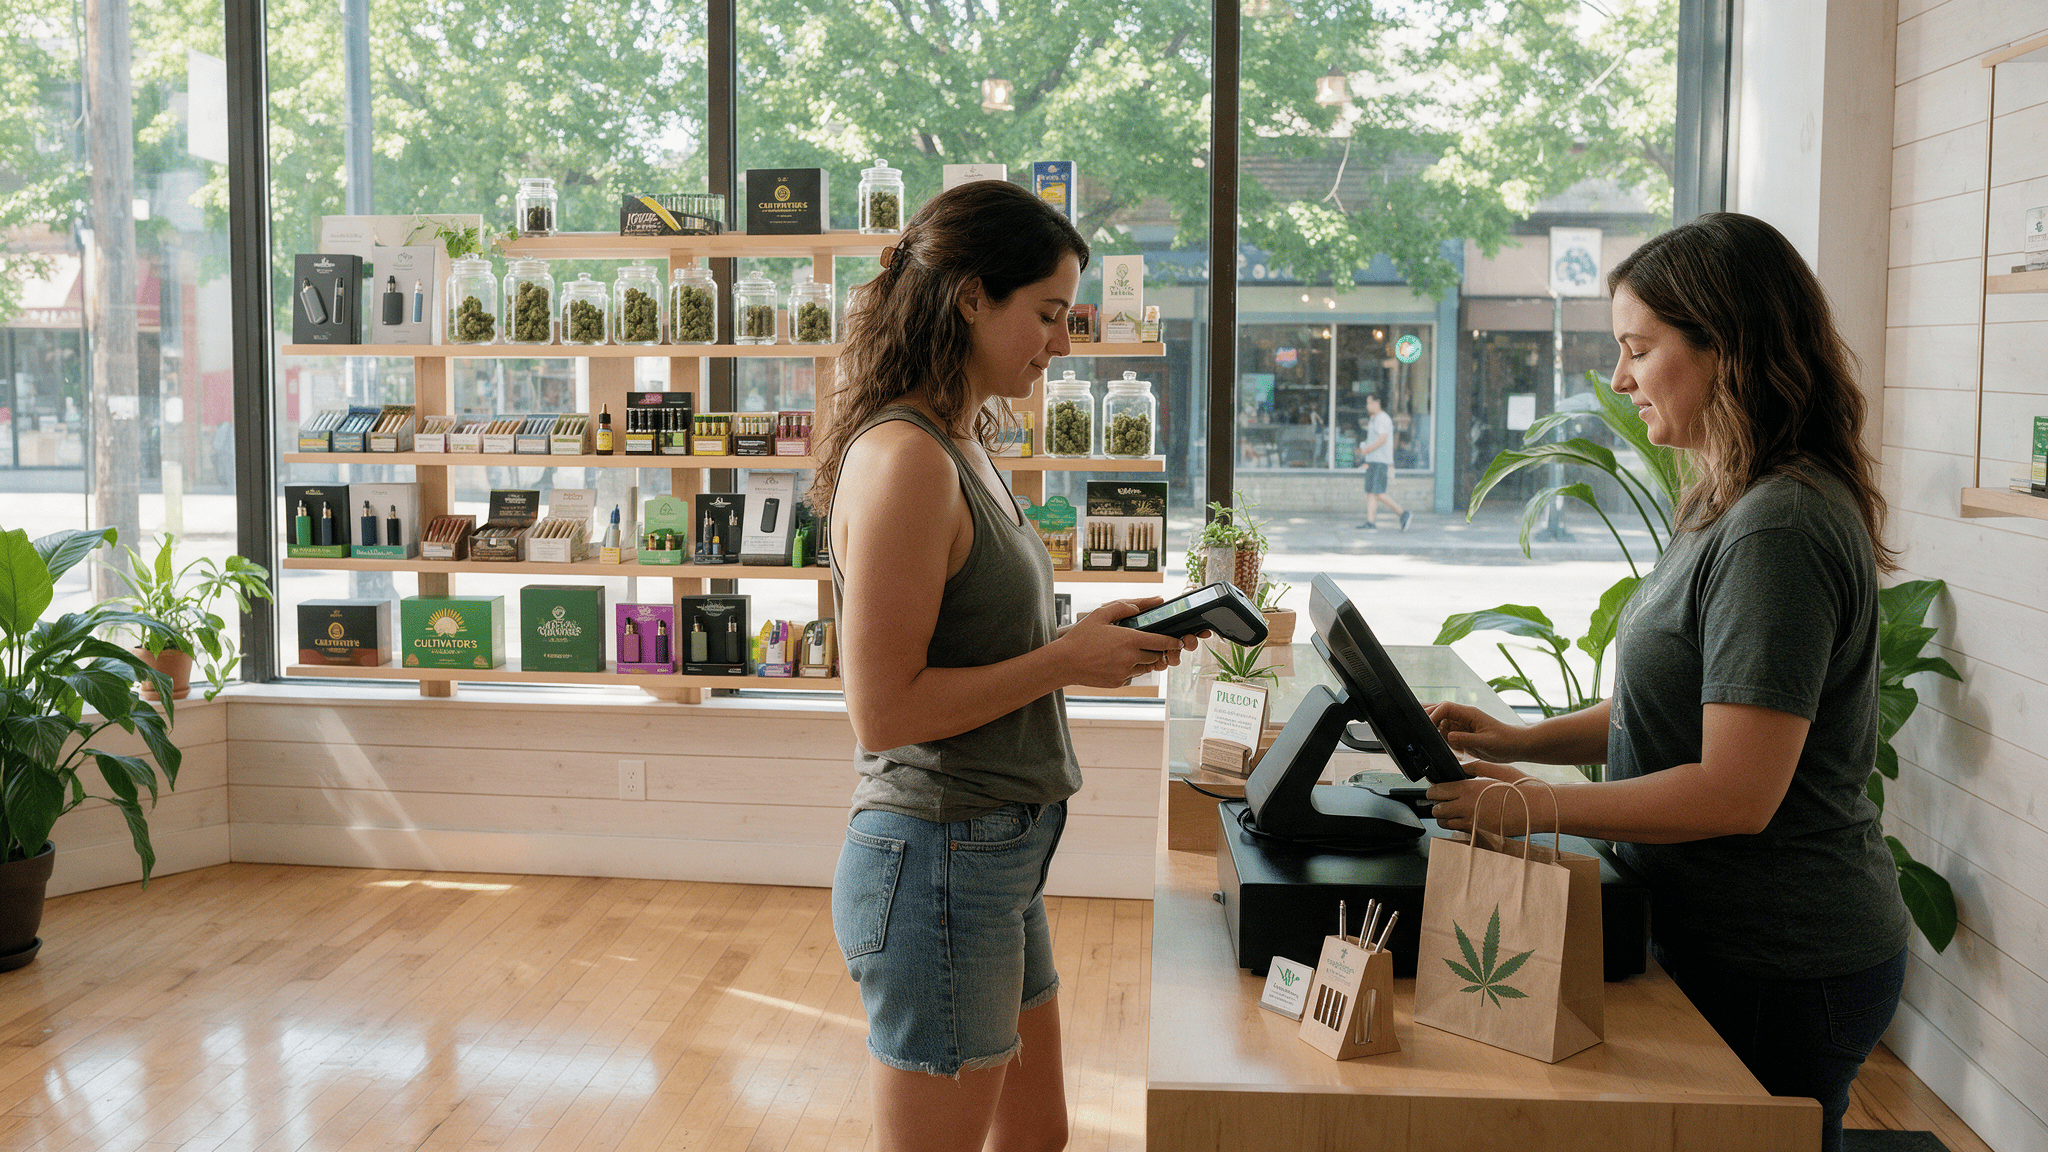
Your budtender rings up the sale, and the customer pays without handing over cash. Our team handles the payment side so your staff stays on the sales floor. We build our service for licensed dispensaries. Our New York dispensary payment processing is built for licensed stores.
Fewer bills change hands at the counter, which means fewer bills to count, store, and move at close. Your closing routine gets shorter, and your safe holds less. Our service is built to support state compliance requirements, and it was designed around how licensed dispensaries operate.
What Your Customers Notice at the Counter
Your customers do not need to plan a cash stop before they visit. With dispensary debit card processing, a customer can pay straight from their bank account at the register instead of hunting for an ATM first. A line moves faster when fewer people count bills at the register, and your staff spends less time making change.
A customer who wants to pay without cash has an option at your counter, and your staff does not have to turn them away. That matters most on busy days, when a long line and a closed ATM cost you sales.
How Every Sale Gets Logged for Audit
Every transaction is logged for audit, with its amount and time. Your records match what happened at the counter instead of depending on handwritten tallies. You keep one record for your non-cash sales. A new manager reads the same log as the manager before them.
New York licensees answer to the Office of Cannabis Management, and your bank can ask about a specific day too. When a question comes in, you pull the log for that day instead of rebuilding it from receipts. Take any question about what New York rules require of your records to a cannabis attorney.
Ready to see how this fits your store? Visit our website and start your application.
How Deposits Reach Your Business Bank Account
Money from your non-cash sales is deposited into your business bank account, and each sale stays in your transaction log. You do not need to track a separate cash trail for those sales. Your bookkeeper works from one record, and your end-of-day numbers come from the same log your deposits do.
A short deposit is easier to trace when you can match it to that day’s logged sales. Your bank may also ask how you record sales, and the log answers that question. Keep the daily log with the rest of your store records.
What Our Service Cannot Change
A payment processor cannot change federal law, and we do not promise that any setup removes federal risk. Card network rules can shift, and cannabis rules in New York can change too.
We build around state compliance requirements and keep a log of each transaction. Your legal, tax, and licensing decisions stay with you and your cannabis attorney or CPA.
What to Gather Before You Apply
Decide which registers will take non-cash sales and which business bank account will receive the deposits. Pull your license details and the name of your point-of-sale system, so you can answer each application question without stopping to look anything up.
Talk with your cannabis attorney or CPA about how non-cash sales fit your books. Their answer settles any tax or licensing question before you apply, and it keeps those decisions with the people qualified to make them.
How to Start Setup for Your New York Store
Setup starts with an application on our website. The application asks how your store runs and which business bank account should receive deposits. Our team works from your answers.
If your New York store runs mostly on cash, we can show you how non-cash payments would fit your counter. Visit our website and start your application with Dispensary Payment Processing.